As private credit increasingly gets packaged for private wealth portfolios, the industry is facing a question that goes beyond yield and access: can products built around illiquid assets meet investors’ growing expectations for liquidity?
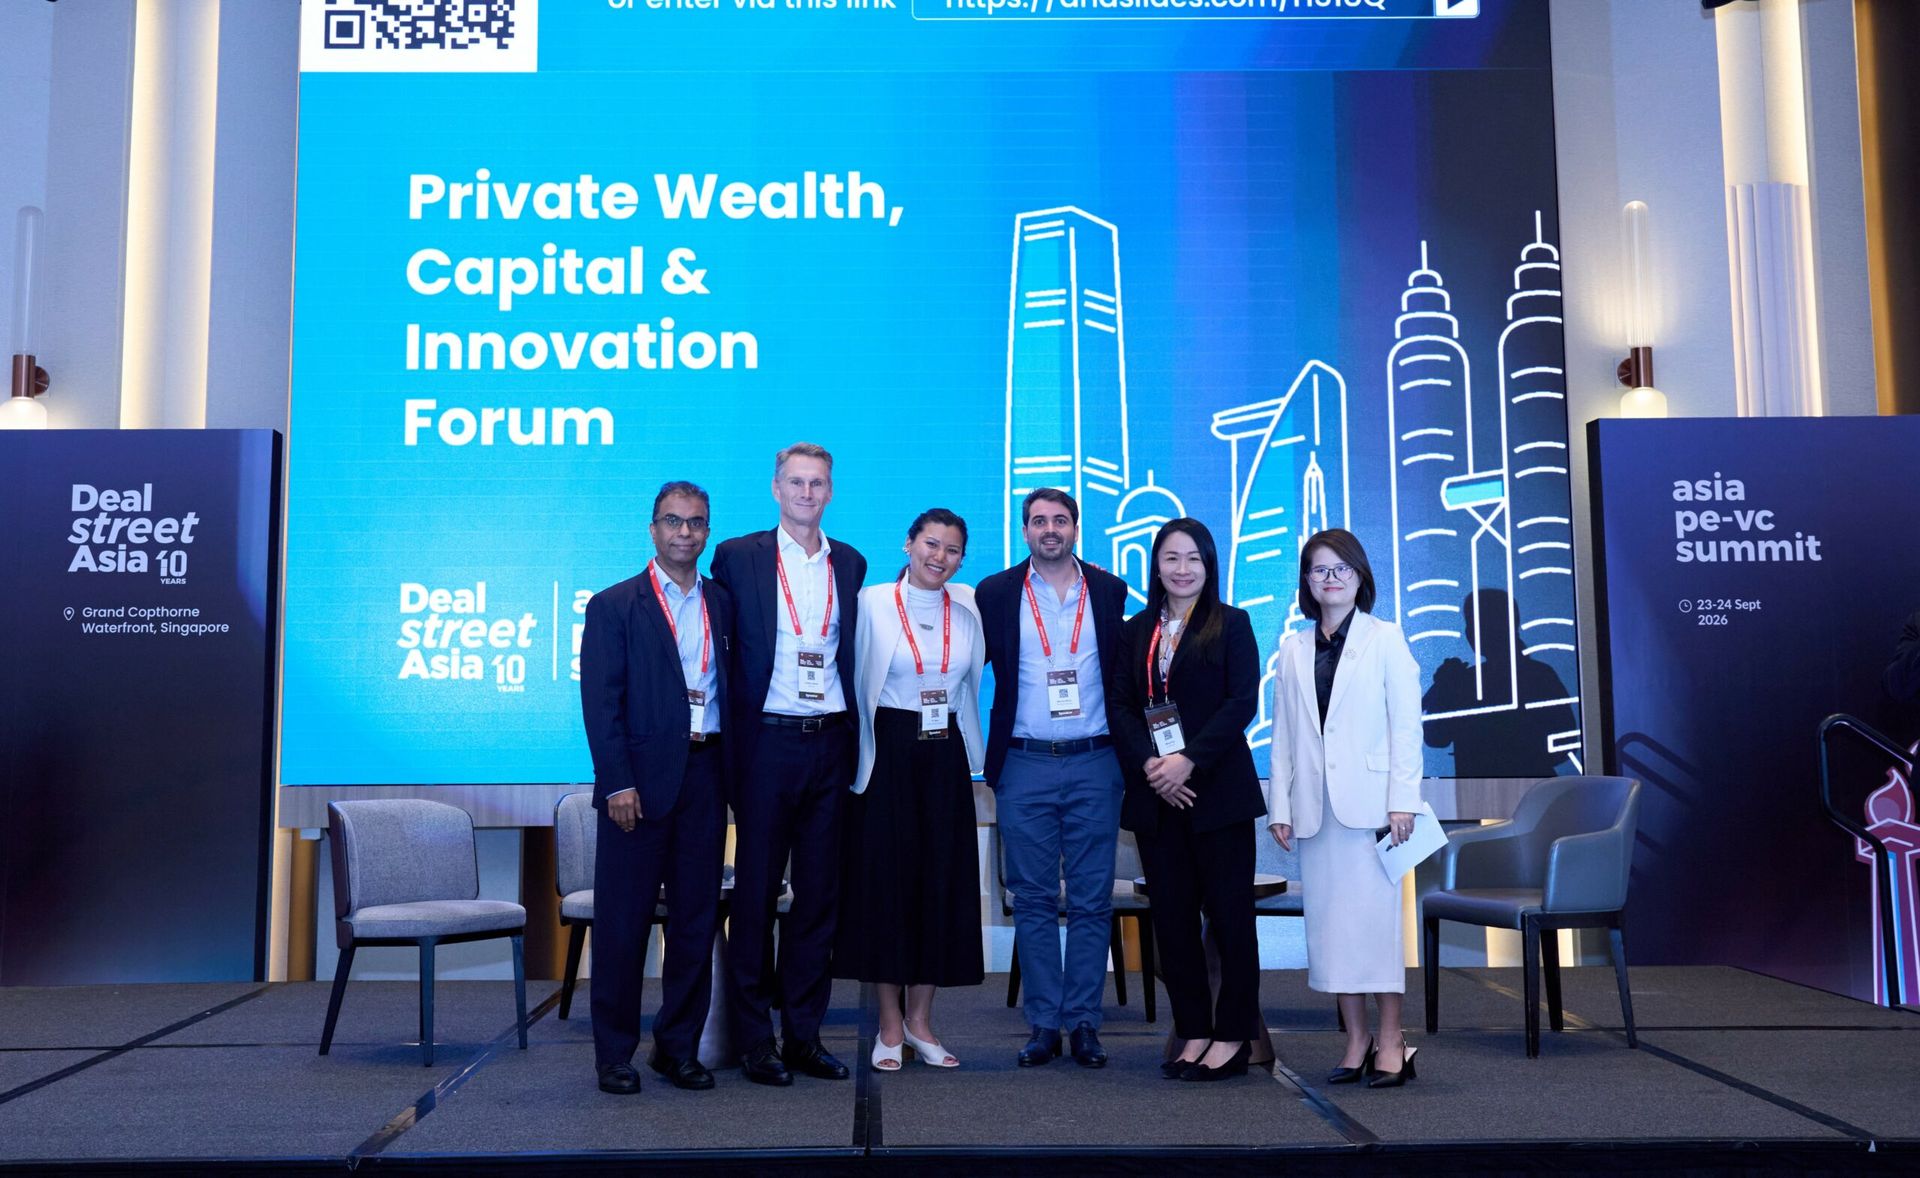
At DealStreetAsia’s Asia PE-VC Summit 2026 in Singapore last week, this question was addressed from different perspectives of fund managers, distribution platforms, fund admins and institutional LPs.
The focus has moved beyond creating access to retail investors and educating the market to how managers construct portfolios, design redemption mechanisms and build financing and operational infrastructure.
Here are the key takeaways from a panel titled ‘Can private credit pass the private wealth’s liquidity test?’
Still delivering
Despite scrutiny around redemption pressures in some parts of the private markets, panellists said they have not seen a fundamental mismatch between the underlying assets and the liquidity provided by their portfolios.
“We are generating about 6-8% natural repayments on a quarterly basis, which are actually in excess of the redemptions we have to provide,” said Johann Santer, Senior Managing Director, Head of Private Wealth APAC at Blue Owl.
Several bank-led default cases may have contributed to greater scrutiny of private credit, but direct lending continues to deliver its attributes including relatively stable, downside-protected returns and higher income generation compared with public markets.
For Blue Owl, which focuses on direct lending to upper-middle-market companies, it is generating a spread premium of around 50 basis points over the SOFR [secured overnight financing rate], according to Santer.
“Even in software, which was controversial six months ago, we’re talking about an all-in yield of 9-10% going forward, which is quite attractive considering where public fixed income markets are trading,” he added.
In evergreen vehicles, even if liquidity is partial, investors who are sensitive to liquidity can still receive a significant proportion of proceeds over the course of a year, according to Mischa Bitton, Head of Alternative Investments, Wealth Solutions at Standard Chartered.
Granite Asia offers a different perspective. The firm operates a closed-end fund but has also attracted capital from private-bank clients. Investors are increasingly recognising that part of the return premium in private credit comes from accepting illiquidity, said Managing Partner Ming Eng.
“It doesn’t mean there’s no liquidity,” she said.
Firms like Granite Asia are funding Asia’s growth. “If you’re doing performing credit, and the companies are growing fast, it’s not unusual for them to be paying us 12-13% coupon, which is distributed to investors.”
Innovative structures
Sashi Nambiar, Muzinich & Co’s Head of Financial Intermediaries and Wealth, Asia, offered some perspectives on how managers can provide differentiated structures to withstand the liquidity test.
Muzinich uses parallel lending or co-lending arrangements with banks, targeting borrowers that are established clients of the banks and have strong cash generation. The firm also keeps leverage levels relatively low in these deals, below 4x, Nambiar said.
“For nearly a decade, we’ve not had a single default. We’ve been able to deliver 6% return in absolute terms year-to-date,” he said.
Another structure is the term loan A, or TLA, in which principal is amortised gradually alongside interest payments. This can create a natural source of liquidity, while capital can be recycled when there are no redemption requests.
The firm also combines public and private credit to create a liquidity sleeve within its portfolios. More liquid, broadly syndicated loans are capped at around 15-20%.
Building benchmarks
Benchmarks for private credit products are not necessarily scarce, but they vary depending on the asset class and structure, according to Bitton.
Standard Chartered works with service providers to establish benchmarks that resemble hedge fund benchmarks and uses them to assess the performance of products available on its platform, he said.
While liquidity terms may be relatively similar across evergreen vehicles, the bank looks beyond redemption terms when assessing products. Its analysis includes performance, portfolio quality, underwriting standards, historical loss rates, the proportion of portfolios valued around par and how a manager would respond when markets come under stress.
In addition, private credit should not be viewed solely through the lens of US secured lending, Bitton said. There is scope to broaden the opportunity set for end clients through greater geographical diversification and exposure to different types of credit.
Liquidity infrastructure
Concerns around liquidity and operational infrastructure are unavoidable as private credit expands into the wealth channel.
Fi Dinh, Managing Director, Head of Fund Finance APAC at MUFG Investor Services, asserted that fund administrators are increasingly focused on operational challenges, including AML and KYC, as evergreen vehicles attract a continuous stream of investors.
Private credit is also far from a homogeneous asset class. From a co-lender perspective, Dinh said the rise of covenant-lite structures and creditor-on-creditor violence in the US are among the trends that lenders need to monitor.
Speaking from another perspective as an institutional LP, she added, concerns remain whether GPs may have to compromise access to certain deals or adapt investment opportunities to make them more digestible for private wealth investors.
“Regardless of the source of liquidity, you cannot make an illiquid asset liquid. But what we can do is to build a more liquidity infrastructure around an illiquid asset,” Dinh said.
Eng agreed from a portfolio manager’s perspective that GPs should not fundamentally alter their strategy simply to accommodate a particular investor base. Instead, the focus should remain on generating exits and distributions. That is particularly important in Asia where deals are often bilateral negotiated.
At the same time, having different types of investors—for Granite Asia—enables the firm to build an ecosystem and draw on relationships to support the growth of private credit in the region and the potential for higher returns.