Diversification in Asia’s private credit market is becoming more deliberate, with managers taking a closer look at market size, risk pricing, and the structures needed to protect downside while preserving upside.
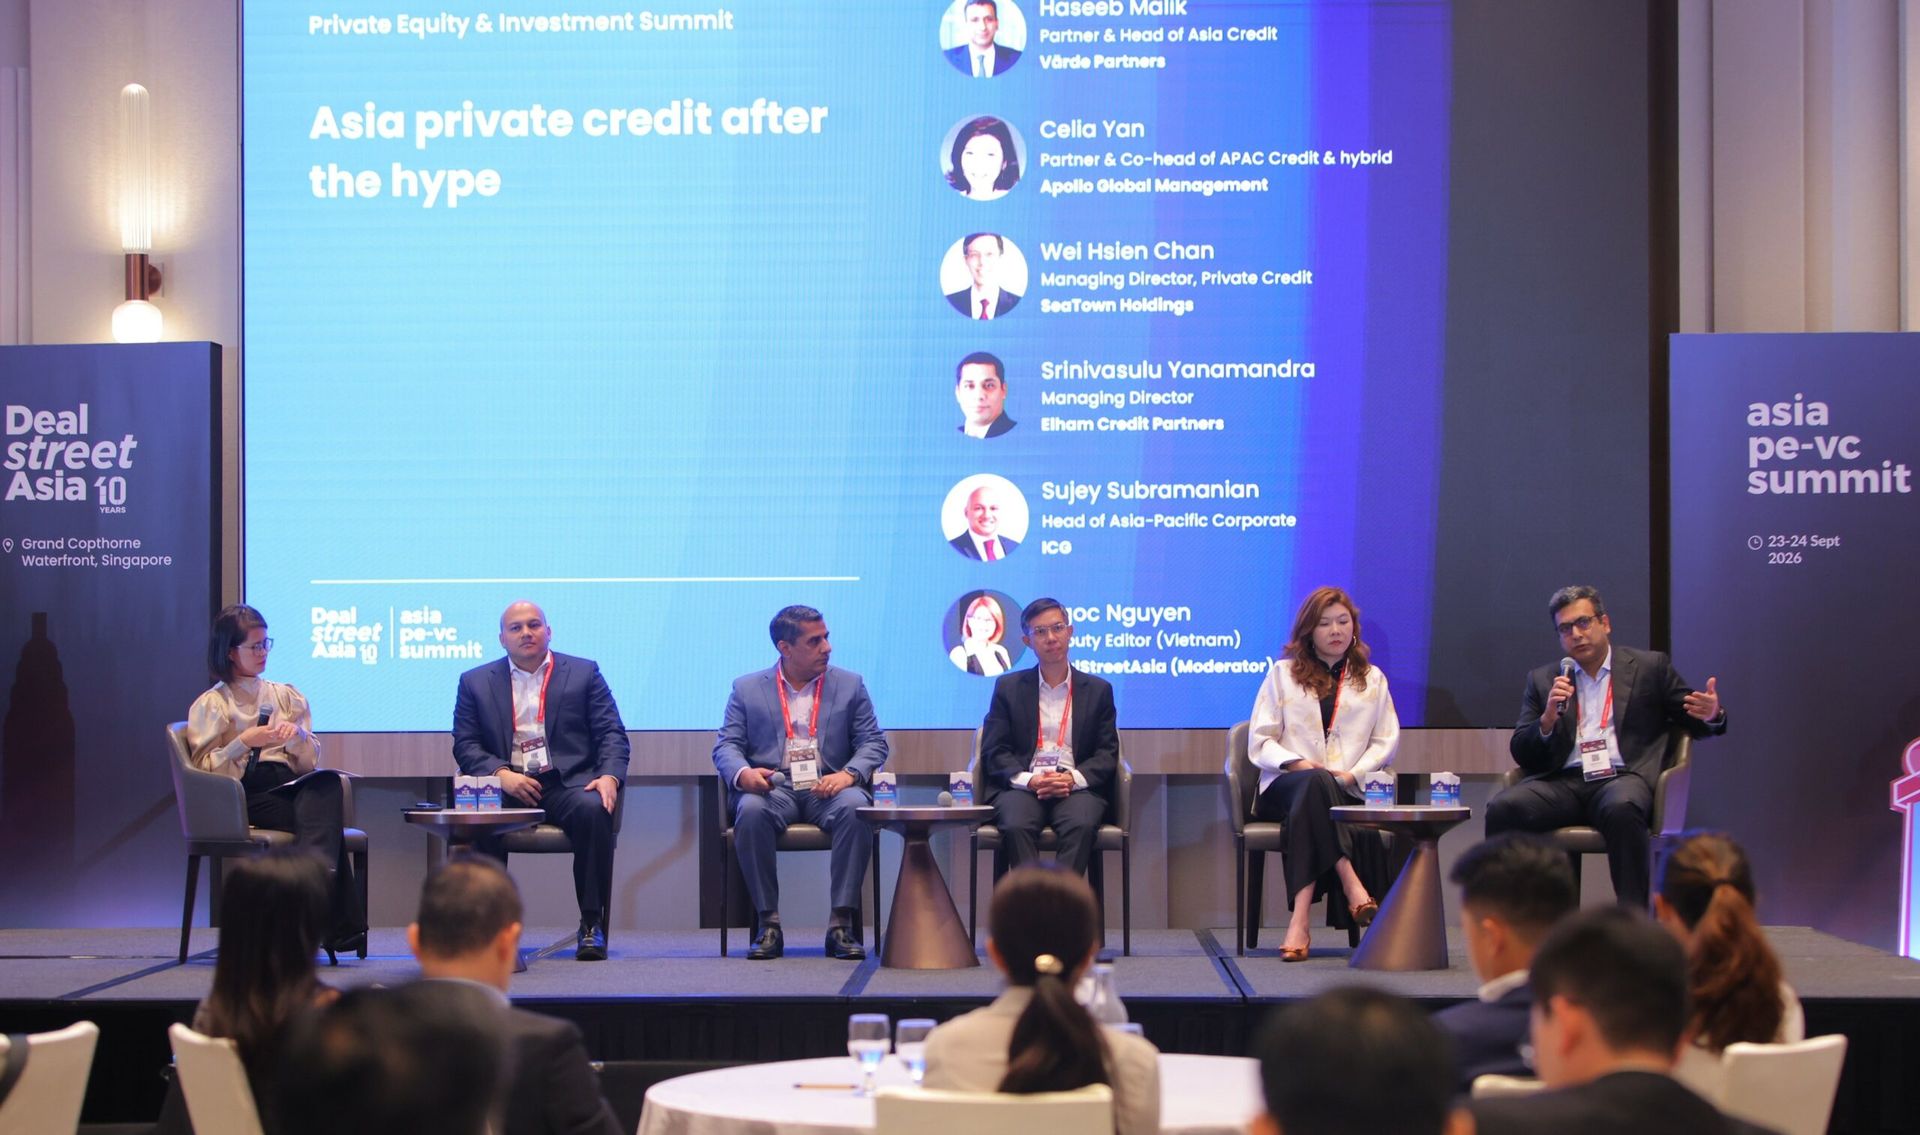
Rather than treating Asia as a collection of markets that can simply be pivoted between, managers are increasingly taking a thematic and top-down approach to portfolio construction, according to investors speaking at DealStreetAsia’s Asia PE-VC Summit 2026 last week.
That shift comes as managers navigate a region where private credit remains relatively small but opportunities are expanding, while returns and risks vary significantly across markets.
Historically, returns from Asia private credit have not been as compelling as those in the US, partly because managers have often assumed that the ability to move across markets would itself provide sufficient diversification, Celia Yan, Partner and Co-head of APAC Credit & Hybrid at Apollo Global Management, said in a panel titled ‘Asia private credit after the hype’.
“But if you are constantly pivoting between markets, you may not have a sufficiently differentiated view to determine how that diversification will actually translate into returns,” Yan said.
A more effective approach to diversification requires a top-down view of where capital should be deployed, including where the right risk-return opportunities lie and whether managers have the talent and expertise on the ground to capture them.
Yan noted that the thematic views in Asia are catching up with global trends. Rather than simply approaching Asia on a country-by-country basis, managers are increasingly identifying structural themes and then assessing which markets are best positioned to deliver the desired returns. “That will definitely improve the return-risk profile for the overall region.”
For much of the past decade, several structural factors have weighed on Asia private credit returns. Sujey Subramanian, Head of Asia-Pacific Corporate at ICG, pointed to the relatively high proportion of capital historically allocated to China, foreign-exchange exposure in emerging markets during periods of rising rates, and the higher allocation to new-economy businesses in Asia compared with other regions.
Looking ahead, however, the backdrop is becoming more constructive. After going through those periods, “the forward curves now look considerably more attractive,” Subramanian said.
He added that the region is delivering improvements in taking on structural challenges such as market fragmentation and banking regulations.
That makes identifying scale in different markets an important consideration for managers building Asia portfolios. Haseeb Malik, Partner & Head of Asia Credit, Värde Partners, opined that certain markets have developed deeper credit cultures, larger economies and more substantial consumer and asset bases, while others remain more fragmented and heavily reliant on banks for credit supply.
The relative size of private credit in the region suggests there is still substantial room for growth. Asia private credit accounts for only 6% of global private credit and an even smaller proportion of the region’s overall credit market.
At the same time, managers are finding a broader range of opportunities.
Premiums on large transactions have compressed somewhat, but pricing remains attractive, observed Wei Hsien Chan, Managing Director, Private Credit, SeaTown Holdings.
Opportunities are widening, he added. For instance, GPs looking for portfolio exits can tap private credit financing in addition to a trade sale or an IPO. “Private credit can become a source of more innovative forms of yields.”
“There is still a significant pipeline of opportunities coming through, but there simply isn’t enough AUM in the funds today to cover all of them,” Chan said.
New underwriting playbook
Some risks — such as currency and illiquidity — can be identified and priced. Others, including enforcement and geopolitical risks, are considerably harder to quantify.
Historically, the Asia opportunity has often been built around the region’s growth potential. Today, downside protection is playing a much greater role in the investment thesis.
It has evolved to understanding the borrower’s needs and potential risks once the manager gets involved, in order to structure the transaction accordingly.
For Apollo, the firm has moved towards larger companies and higher-quality credits in the region. Recent transactions include a financing for Japan’s Nippon Sheet Glass, as well as a hybrid transaction involving The Executive Centre. The latter illustrates the increasingly bespoke nature of private credit, with managers looking beyond a conventional financing requirement to identify the underlying problem a company is trying to solve and then designing a flexible solution around it.
“That is particularly important when it comes to underwriting,” Yan said.
ICG has similarly maintained a focus on higher-quality businesses, developed Asia and managing currency exposure, with an emphasis on companies that have credible exit routes.
But while that core approach has remained consistent, the way ICG seeks to capture upside has evolved.
Fifteen to 20 years ago, sponsor-backed transactions and mezzanine financing offered attractive opportunities, Subramanian said. Today, however, it is harder to generate alpha from those transactions.
ICG has increasingly explored structures such as convertible debt, preference shares and debt with warrants, which can provide greater downside protection while retaining participation in potential upside.
“To generate the target returns, you still need enough deals to reach the upside case,” Subramanian said. “The question is how you crystallise that upside, particularly when it can be difficult for companies to reach the scale required for an IPO. So we have been continually refining our strategies around how to capture that upside.”
Another way managers are seeking to navigate Asia’s fragmented markets is through partnerships.
Srinivasulu Yanamandra, Managing Director at Elham Credit Partners, said the firm leverages its parent Hillhouse Capital’s network for deal origination, due diligence and insights into emerging sectors and market-specific dynamics.
“It’s the knowledge that cannot simply be found in a book, and it is an important part of how we differentiate ourselves and generate alpha,” he said.
Partnerships can also provide access to markets where a manager has investment conviction but does not yet maintain a dedicated team on the ground. Late last year, Elham partnered with Daiwa Securities-backed Digital Climate Group to explore private credit opportunities across Asia-Pacific, initially focusing on Japan.
As the regional market continues to develop, Yanamandra sees substantial room for private credit to grow. “As long as there are no global mishaps impacting the people’s view on private trade in Asia, there is ample runway to support rapid private credit growth.”
For Malik, the next stage of development will depend partly on the continued deepening of Asia’s capital markets.
The industry will need to develop greater depth and breadth, with managers continuing to scale and increasingly participating in larger, globally relevant transactions, he said.